
Protect Your London Renovation: 12–24 Month Builder Warranties in the UK
A builder warranty is the contractor’s written promise to put right faults in their own work, usually for 12 to 24 months after completion. It sits alongside, not instead of, your statutory rights under the Consumer Rights Act 2015. Before any work starts on your extension, loft conversion or refurbishment, get the warranty in writing and ask whether it is insurance-backed.
TL;DR:
A workmanship warranty covers defects related to labor and installation but does not include issues caused by materials or natural wear and tear.
Most domestic warranties last between 12 and 24 months, but statutory rights under the Consumer Rights Act 2015 provide up to six years for breach recourse.
Insurance-backed guarantees are optional policies that ensure payout even if the builder goes bankrupt, and homeowners should request them for larger projects.
Documented evidence and clear communication are essential for resolving defects after construction, especially if the warranty has expired.
Always verify warranty scope, start dates, and claim procedures in writing before signing a contract, and consider legal rights that extend beyond warranty periods.
Table of Contents
What does a workmanship warranty cover, and what’s usually excluded?
What are my statutory rights if a workmanship warranty runs out?
What is an insurance-backed guarantee and when should you insist on one?
What should you do if you discover a defect after the work is finished?
Tenen Ltd’s perspective: how a reputable London contractor handles warranties
What is a builder workmanship warranty in the UK?
A workmanship warranty is a contractual promise from your builder, not a piece of legislation. It typically states that they will return to fix defects arising from poor installation or incomplete work within a defined period, at no extra cost to you. Good contracts spell out exactly what “defect” means, who assesses it, and how quickly the builder must respond once notified.
This is where confusion often creeps in. Homeowners assume a workmanship warranty behaves like a manufacturer’s product guarantee, covering everything from cracked tiles to a failing boiler. It does not. A workmanship warranty covers the quality of labour, the way something was installed or finished, rather than the materials themselves, which usually carry a separate manufacturer guarantee.
Whatever your written warranty says, it never overrides your legal position. The Consumer Rights Act 2015 already obliges any trader to perform services with reasonable care and skill, and that obligation exists whether or not a contract mentions it.
A workmanship warranty is a promise about labour quality, not materials.
It cannot reduce rights you already hold under consumer law.
A short warranty period (say, 12 months) doesn’t mean your legal recourse ends there.
Always check the wording defines the start date, scope, and how to make a claim.
What does a workmanship warranty cover, and what’s usually excluded?
Most workmanship warranties on domestic refurbishment jobs cover faulty installation, poor finishing, and elements the builder was directly responsible for fitting, such as a leaking shower tray or an uneven plaster wall. What they exclude tends to matter more in practice than what they include.
Typically, covered:
Installation errors (misaligned doors, leaking joints, faulty tiling adhesion)
Incomplete or missing finishes agreed in the specification
Defects traceable to the builder’s own labour, not third-party products
Commonly excluded:
General wear and tear
Damage from inadequate maintenance after handover
Faults in materials you supplied yourself
Movement or settlement typical of any new structural work
Duration varies by trade. A general refurbishment might carry a 12-month workmanship guarantee, while some specialist trades or manufacturer-backed products (certain roofing systems, for example) run to several years. Builders sometimes offer a shorter defects rectification period, commonly six to twelve months, as an informal snagging window before the fuller warranty terms apply.
Pro Tip: Before signing anything, ask your builder to confirm three things in writing: the exact start date of the warranty, precisely what “workmanship” excludes, and the process for logging a claim. Vague wording like “reasonable defects” is a red flag; insist on specifics.
What are my statutory rights if a workmanship warranty runs out?
Your statutory rights don’t expire when the warranty period ends. Under the Consumer Rights Act 2015, a trader must carry out services with reasonable care and skill, and that duty applies for the life of a standard contract claim, not just the warranty window. The House of Commons Library briefing on rogue builders confirms all domestic building work falls under this Act, though there’s still no compulsory licensing scheme for builders in England and Wales.
For most simple contracts, the relevant limitation period is six years from the date the breach occurred, meaning you can pursue a claim for defective work long after a 12-month warranty has lapsed, provided you act within that window. This matters enormously for issues that surface slowly, such as a roof leak that only becomes obvious after two winters.
A written warranty is a convenience, not your only protection.
The Consumer Rights Act 2015 applies regardless of what the contract says.
Six years is the general limitation period for straightforward contract disputes.
Keep evidence and correspondence dated, because timing matters if a dispute escalates.
Practically, this means don’t panic the moment a warranty expires. Gather your paperwork, note when the defect first appeared, and get advice on whether you’re still within the limitation window before assuming you have no recourse.
What is an insurance-backed guarantee and when should you insist on one?
An insurance-backed guarantee (IBG) is a policy where an insurer, not the builder, stands behind the warranty. If your contractor goes into liquidation or simply disappears, the insurer covers the cost of putting defects right, rather than leaving you with a worthless promise from a company that no longer exists.
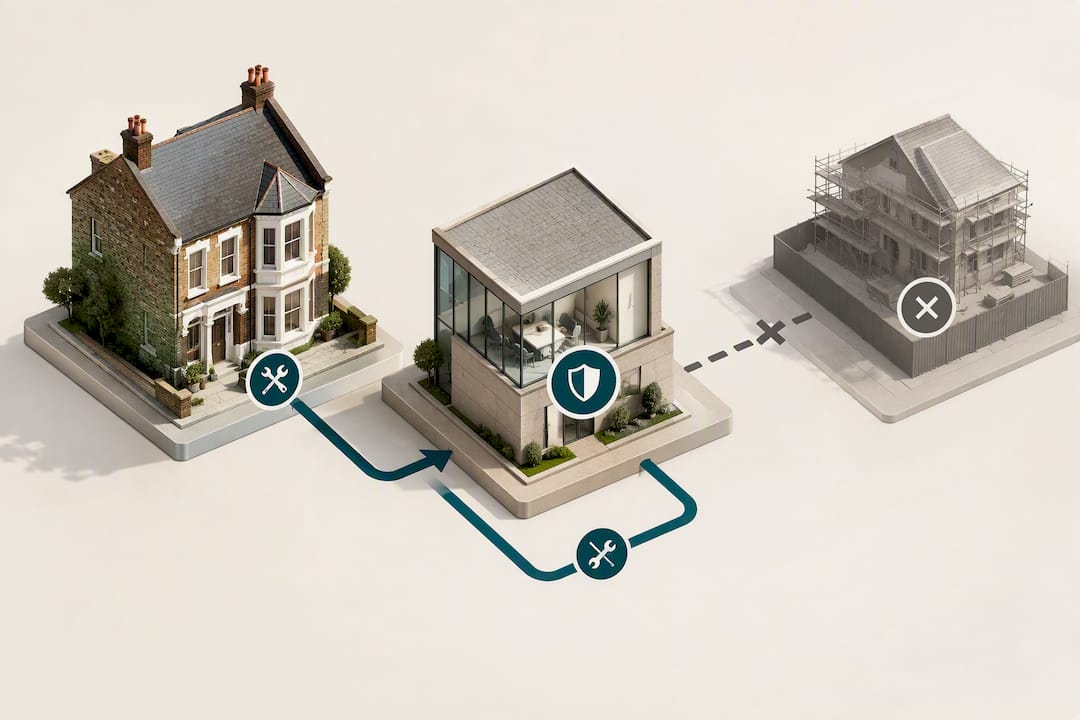
IBGs aren’t automatically included on every domestic renovation. QualityMark’s guidance on home improvements makes clear they’re an optional product homeowners should actively request, particularly on larger jobs like extensions or full refurbishments where the financial exposure is significant.
Before accepting one, check:
The exact policy wording, not just a summary or a logo on a brochure
The insurer’s name and a direct contact for claims, not only the builder’s word
Whether the guarantee transfers to a new owner if you sell the property
Exclusions and any excess payable when you make a claim
An IBG is only as strong as the insurer behind it. Ask for evidence of a previous payout or claims precedent if you can, since a policy that has never been tested is harder to trust than one with a track record. Cost varies by project size and is usually built into the overall quote rather than charged as a separate line item, so raise it early during quoting, not after you’ve signed.
What should you do if you discover a defect after the work is finished?
Document everything immediately. Take date-stamped photographs and a short video walkthrough of the defect. Note the date you first noticed it and any conversations you’ve had about it.
Check your paperwork. Pull out the original contract, the warranty document, and any completion certificates (electrical, gas, building control) that relate to the affected area.
Notify the builder in writing. Describe the defect clearly, reference the warranty clause if relevant, and set a reasonable deadline for them to respond and remedy the issue. Email is fine, but keep every reply.
Keep a running log. TrustMark’s guidance recommends recording every communication, milestone, and promised action, because a clear paper trail is what makes escalation credible if it comes to that.
Check your payment method. If you paid any part of the project by credit card and the cost of that item or service was between £100 and £30,000, Section 75 of the Consumer Credit Act 1974 can make your card provider jointly liable if the builder fails to deliver.
Escalate if the builder refuses to engage. Contact Citizens Advice or Trading Standards for guidance, and consider the small claims court for disputes under the relevant financial threshold if informal routes fail.
Pro Tip: Send your written notice by email and request a read receipt, or follow up with a short message confirming they’ve seen it. A builder who later claims they “never received” your complaint has a much weaker case if you can prove otherwise.
Tenen Ltd’s perspective: how a reputable London contractor handles warranties
Warranty documentation shouldn’t be an afterthought bolted on at the end of a project. At Tenen Ltd, a London-based construction and refurbishment company working across Fulham, Chelsea, Kensington, Chiswick, Hammersmith and Notting Hill since 2006, warranty terms are agreed and written down before work begins, not negotiated after a defect appears.
That sequencing matters more than most homeowners realise. A contractor confident in their own workmanship has no reason to keep warranty wording vague, and clients across West and Central London consistently expect that level of clarity when commissioning extensions, loft conversions and full refurbishments. Attention to detail on paper tends to reflect attention to detail on site.
— Mateja
How Tenen Ltd can help with your next project
If you’re planning an extension, loft conversion or full refurbishment anywhere in West or Central London, request a site survey and ask for a written workmanship warranty as standard practice, not a favour. A fixed, itemised quote with clear warranty terms attached gives you something concrete to hold a contractor to, rather than a verbal promise that’s impossible to enforce later.
The company provides project oversight and in-house execution without subcontractor chains, so warranty accountability sits with one team throughout, not scattered across multiple trades. Explore the full property refurbishment service, browse loft conversion options, or get details on home extensions if you’re weighing up how to add space rather than move. Whichever project you’re considering, confirm the warranty wording and whether an insurance-backed guarantee applies before you accept any quote, and don’t be shy about asking a contractor to put both in writing.
Where to check the facts yourself
Section 75, Consumer Credit Act 1974, for credit card protection on qualifying purchases
Citizens Advice: before you get work done on your home, for pre-contract checks
TrustMark: what to do if you’re unhappy with building work, for escalation steps
House of Commons Library briefing on rogue builders, for the statutory backdrop
For a wider vetting checklist before signing any contract, SzopaLabs’ contractor verification guide offers a useful structured approach, though it’s worth cross-checking against UK-specific consumer law.
Sources
FAQ
Is a builder legally required to give a workmanship warranty?
No. There’s no legal requirement for a builder to offer a written workmanship warranty in the UK, though reputable contractors provide one as standard practice. Your statutory rights under the Consumer Rights Act 2015 apply regardless of whether a warranty exists.
How long does a typical builder warranty last?
Most domestic refurbishment warranties run for 12 to 24 months, though some trades or manufacturer-backed products last longer. Statutory remedies can still apply for up to six years from the breach, separate from any written warranty term.
What’s the difference between a workmanship warranty and an insurance-backed guarantee?
A workmanship warranty is a promise from the builder to fix their own defects. An insurance-backed guarantee adds an insurer behind that promise, so the guarantee still pays out if the contractor ceases trading.
Can I claim on my credit card if my builder refuses to fix defects?
Yes, if you paid at least part of the cost by credit card and the item or service cost between £100 and £30,000. Section 75 of the Consumer Credit Act 1974 can make your card provider jointly liable alongside the builder.
Does Tenen Ltd provide a written workmanship warranty?
Warranty terms are agreed in writing before work begins on extensions, loft conversions and refurbishments. Specific terms and current service details are available on the Tenen Ltd services pages.
Recommended
Comments